The ongoing Middle East conflict is reinforcing a difficult reality for import-dependent energy economies such as Bangladesh.
With global oil prices showing renewed volatility and LNG supply chains facing heightened uncertainty, the issue is no longer only about short-term market pressure. It is increasingly about energy resilience, industrial continuity, and long-term economic preparedness.
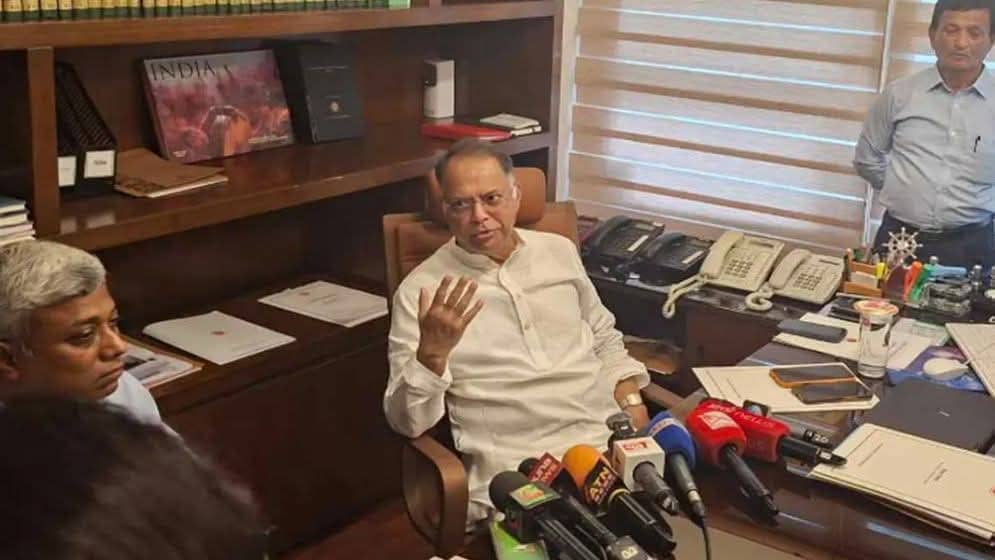
Against this backdrop, State Minister for Power, Energy and Mineral Resources Iqbal Hasan Mahmud Tuku moved to reassure the public, stating:
“A gap has developed between demand and supply. Demand has increased. We have been supplying at the same rate, and that supply is continuing. When demand rises, a temporary crisis can occur. It’s a matter of common understanding.”
He also emphasized that Bangladesh has sufficient fuel oil stocks and urged consumers not to make unnecessary purchases.
That reassurance is important. But so is the larger strategic picture.
Bangladesh’s daily gas demand is roughly 4 billion cubic feet, while domestic production remains around 1.7–1.8 billion. The shortfall is being met through imported LNG, creating significant exposure to external supply disruptions and international price shocks.
For business and policy leaders, the message is clear:
this is not simply a temporary supply issue. It is a reminder of the structural risks that come with concentrated import dependence.
If disruptions in global fuel supply persist, the implications could extend well beyond the energy sector—affecting industrial productivity, export competitiveness, subsidy burdens, and overall macroeconomic stability.

- Md. Saiful Islam Journalisthttps://thebusinessin.com/author/saifuljournalist/
- Md. Saiful Islam Journalisthttps://thebusinessin.com/author/saifuljournalist/
- Md. Saiful Islam Journalisthttps://thebusinessin.com/author/saifuljournalist/
- Md. Saiful Islam Journalisthttps://thebusinessin.com/author/saifuljournalist/