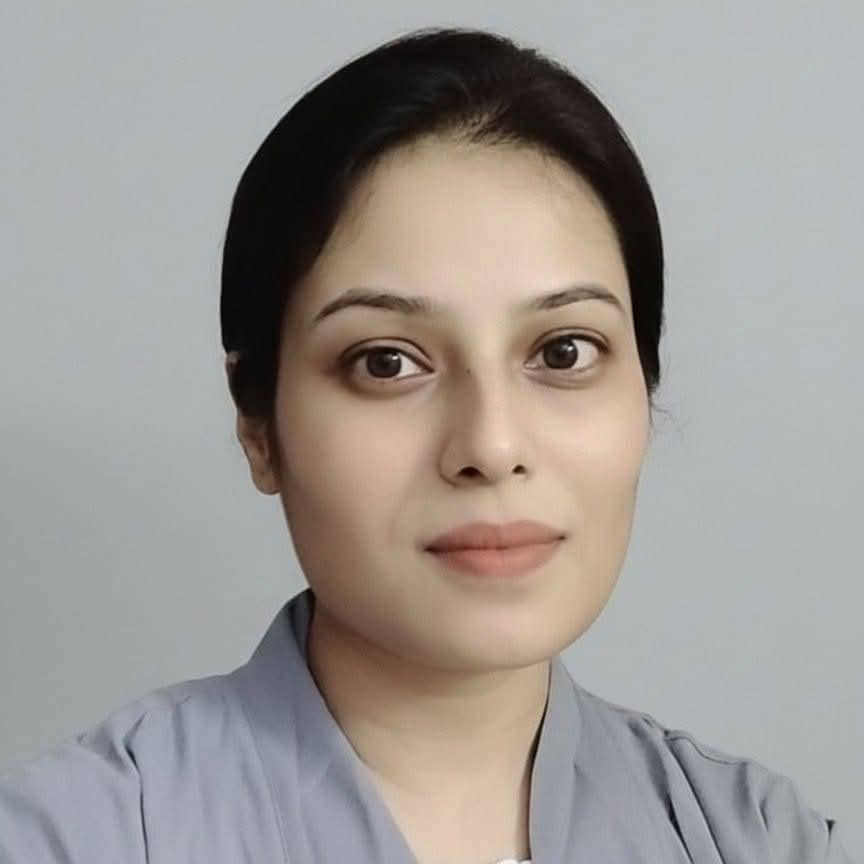
Aleen Mahbub
In a narrow lane of Narayanganj, a small garment subcontractor runs his business with just eight workers and a handful of sewing machines. Orders come regularly from larger factories, payments arrive late, and cash flow remains unpredictable. Yet, despite a steady business, he has never accessed a formal bank loan.

“I don’t have land in my name,” he says quietly. “So the bank says I don’t exist.”This is not an isolated story. It is, in many ways, the defining reality of Bangladesh’s small and medium enterprise (SME) sector a sector that powers the economy, yet remains largely invisible to the formal financial system.
SMEs are widely regarded as the backbone of Bangladesh’s economy. They contribute significantly to employment generation and industrial diversification, spanning sectors from light engineering and agro-processing to e-commerce and handicrafts. According to estimates, SMEs account for over 25% of GDP and employ millions across urban and rural areas.
Institutions like Bangladesh Bank have recognized their importance, introducing refinancing schemes, policy incentives, and dedicated SME lending targets for commercial banks. On paper, the ecosystem appears supportive. But the ground reality tells a different story.
In Bangladesh, many small businesses are profitable and active, yet they struggle to grow because of a major problem called “informality.” This means that even though these businesses exist and make money, they do not have formal records like bank statements or audited financial reports. This lack of data creates a big wall between entrepreneurs and the loans they need.
According to recent research from 2023–2024, banks find it nearly impossible to measure the risk of lending to these SMEs because most of them operate entirely with cash and do not have official tax documents (like TIN ). Since their money doesn’t flow through a bank, they have no “financial footprint” to prove they are reliable.
The consequence of this situation is a clash between risk and reality. In the banking world, if a bank cannot measure the risk using clear data, they simply will not give the loan. As a result, even a very successful small business is often rejected just because its success is not written on paper. To fix this, Bangladesh needs to move toward “Alternative Credit Scoring.” This means using other types of data such as mobile banking history, utility bill payments, and records from suppliers to judge a business’s creditworthiness. By closing this information gap and using digital data, we can help informal shops become formal businesses, allowing the “missing middle” to finally access the capital they deserve.
The SME sector in Bangladesh is currently caught in a cycle known as the “Informality Trap.” While these businesses are the heartbeat of the economy, a large portion of them operate without formal records. Many entrepreneurs run profitable shops and factories, but because they do not maintain audited financial statements or formal tax documents, they remain “invisible” to the banking system. In the world of finance, if a business cannot provide verifiable data, banks cannot measure the risk. Consequently, even a successful entrepreneur is often denied a loan simply because their business exists in reality but not on paper.
This problem is made worse by the banking sector’s heavy reliance on collateral-based lending. In Bangladesh, it is almost impossible to get a loan without providing land or property as security. This creates a structural mismatch for modern, “asset-light” businesses such as those in digital commerce or the service sector. These companies may have strong revenues and loyal customers, but they lack physical assets like land. While the rest of the world is moving toward alternative models like invoice financing or cash-flow-based lending, Bangladesh’s system still prioritizes physical wealth over business capability.
The cost of this financial exclusion is high for the national economy. When formal bank loans are unavailable, SMEs are forced to turn to informal sources, including family, friends, or local moneylenders. While microfinance institutions have helped the very poor, they often cannot provide the large amounts of capital a growing SME needs. As a result, many small business owners end up borrowing at extremely high interest rates—sometimes reaching 30% to 40%. This increases the cost of doing business and prevents small enterprises from scaling up. To unlock the true potential of Bangladesh’s economy, the system must transition from checking for land titles to analyzing digital footprints and business performance.
Bangladesh has a clear gap in its financial system, often called the “missing middle.” On one side, micro-enterprises get support from microfinance institutions. On the other side, large corporations easily get loans from formal banks. However, Small and Medium Enterprises (SMEs) are stuck in the middle. They are too big for microfinance but often considered “too risky” or “too small” for traditional bank loans.
This is a major problem because SMEs are the backbone of the economy. They create the most jobs and have great potential to grow. However, a strange paradox exists in the banking sector. Banks often say they want to lend to SMEs, but they find it difficult to manage the risks and paperwork. At the same time, entrepreneurs say they want to borrow money to expand their businesses, but they cannot access bank loans because they lack the required collateral (like land or property) or formal documents.
There is a huge gap between the banks’ willingness to lend and the entrepreneurs’ ability to access funds. To fix this, we need to change how we view SME lending. Instead of relying only on collateral, banks should use digital records, transaction history, and business potential to judge creditworthiness. If Bangladesh can bridge this “missing middle” gap, it will help SMEs grow faster, create more jobs, and boost the country’s overall economic development
Amid these challenges, financial technology (fintech) is emerging as a potential game-changer.Digital financial services, mobile transactions, and data analytics are creating new pathways for credit assessment. By analyzing alternative data—such as transaction history, mobile usage, utility payments—lenders can build a more accurate risk profile of SMEs.
Bangladesh Bank has already initiated steps toward digital financial inclusion, including e-KYC and online lending frameworks. However, the adoption remains limited.Challenges include:Data fragmentation,Lack of interoperability between systems
Bangladesh does not lack good policies; it lacks effective implementation. Over the years, the government has launched many initiatives to increase SME lending, support women entrepreneurs, and promote financial inclusion. However, a significant gap remains between paper and practice. As many business owners say, “The policy exists, but the access does not.” To bridge this gap, simply giving orders is not enough. We need to align incentives for banks, create risk-sharing mechanisms, and establish strong monitoring systems to ensure that funds actually reach the businesses that need them most.
To truly unlock the potential of SMEs, Bangladesh must rethink its entire approach to financing. First, the definition of collateral needs to change. Banks should recognize “movable assets” such as machinery, products in stock, and unpaid invoices as valid security for loans. This would help “asset-light” businesses that do not own land. Second, government-backed Credit Guarantee Schemes must be strengthened to reduce the fear of risk for banks. Third, by using Fintech and Data-Driven Lending, banks can look at a business’s digital footprint and cash flow instead of just paper documents. Finally, entrepreneurs should be encouraged to join the formal system through tax benefits and easier registration processes.
In conclusion, SMEs are not just a small part of the economy; they are its foundational core. They drive innovation, create millions of jobs, and ensure economic resilience. However, as long as they remain “financially invisible,” their true potential will remain unused. The challenge for Bangladesh is not just about providing more money; it is about changing how the financial system measures value and trust. An economy cannot reach its full speed if its most dynamic players are left outside the gate. It is time to treat SMEs not as a risk, but as the primary engine of our national growth.
Writer : Aleen Mahbub is an Author focused on entrepreneurship, SME growth, and business insights.

- Md. Saiful Islam Journalisthttps://thebusinessin.com/author/saifuljournalist/
- Md. Saiful Islam Journalisthttps://thebusinessin.com/author/saifuljournalist/
- Md. Saiful Islam Journalisthttps://thebusinessin.com/author/saifuljournalist/
- Md. Saiful Islam Journalisthttps://thebusinessin.com/author/saifuljournalist/