🏦 Sandhani Life: Why Growth Has Slowed—and How Recovery Can Happen
By Staff Correspondent | October 2025
For over three decades, Sandhani Life Insurance Company Limited has been one of Bangladesh’s most respected names in life insurance.
Known for its legacy of trust and financial protection, the company now finds itself navigating a challenging period of slow growth, rising costs, and shifting consumer expectations.
Yet, under the leadership of its dynamic and experienced Chief Executive Officer, Mr. Nimai Kumar Saha, Sandhani Life appears poised for a gradual but determined turnaround.
🔹 An Industry in Transition
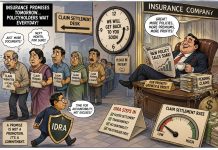
Bangladesh’s insurance industry has long faced systemic challenges — delayed claim settlements, weak transparency, and limited regulatory discipline.
As a result, public confidence in life insurance has eroded, policy sales have slowed, and premium growth has stagnated.
Like many of its peers, Sandhani Life has been affected by these structural weaknesses:
-
Claim settlement delays have hurt customer confidence.
-
Customer retention has weakened.
-
Agent networks, once the lifeblood of the business, have struggled to adapt to the digital age.
However, with renewed leadership and a reform-driven approach, the company is taking visible steps toward rebuilding trust.
🔹 Internal Pressures: Cost, Investment & Product Gaps
 1️⃣ Escalating Costs vs. Declining Income
Legacy operational systems and traditional agent-based sales networks have led to high administrative expenses.
Meanwhile, new premium generation has slowed, creating a profitability squeeze.
2️⃣ Limited Investment Returns
Sandhani Life’s investment portfolio remains heavily concentrated in government bonds and fixed deposits, which have delivered lower real returns amid inflation and rate fluctuations.
3️⃣ Outdated Product Mix
In an era where consumers demand flexible, tech-enabled, and short-term insurance solutions, the company’s product base remains heavily traditional.
New market segments — such as microinsurance, health coverage, and takaful (Islamic insurance) — have yet to reach full commercial scale.
🔹 Leadership Spotlight: Nimai Kumar Saha
At the heart of Sandhani Life’s revival story is its Chief Executive Officer, Mr. Nimai Kumar Saha — a seasoned insurance professional with a rare blend of technical expertise and people-driven leadership.
Born in 1965 in Narail, Mr. Saha holds a Master’s degree in Accounting from the University of Dhaka.
He brings over 34 years of experience in financial management and control functions within Bangladesh’s life insurance sector.
His leadership philosophy is simple yet powerful — “Restoring trust through efficiency, technology, and service excellence.”
🔹 Strategic Reforms Under His Leadership
✅ Digital Transformation – The “i-Life” Platform
Under Mr. Saha’s direction, Sandhani Life launched “i-Life”, a comprehensive digital platform that enables customers to buy policies, pay premiums, track claims, and view policy information online.
This initiative has significantly improved service accessibility, reduced administrative costs, and modernized customer engagement.
✅ Partnership with CRAB for Transparency
The company recently partnered with the Credit Rating Agency of Bangladesh (CRAB) to enhance its financial rating and governance credibility.
This move aligns with global best practices and reassures investors about Sandhani Life’s financial discipline.
✅ Cost Optimization and Internal Reforms
Mr. Saha has introduced rigorous expense control measures, streamlined operational processes, and implemented performance-based management systems to strengthen accountability at every level.
✅ Customer-Centric Service Model
He has emphasized faster claim turnaround times, proactive grievance resolution, and enhanced service delivery as core pillars of customer retention.
His belief is clear — “An insurance company’s true reputation lies in how quickly and fairly it serves its policyholders.”
🔹 A Sector-Wide Reform Wind
Bangladesh’s insurance regulator, the Insurance Development and Regulatory Authority (IDRA), has launched sweeping reforms focused on risk-based supervision, e-policy verification, and timely claim settlements.
Mr. Saha views these regulatory measures not as constraints but as opportunities to align Sandhani Life with a new era of compliance, credibility, and customer trust.
🔹 The Road Ahead: Key Performance Indicators
| Indicator | What to Watch For |
|---|---|
| Profitability | Cost reduction and improved investment yield. |
| Premium Growth | Expansion into health, microinsurance, and takaful lines. |
| Claim Settlement Speed | Enhanced efficiency through e-tracking. |
| Customer Experience | Wider adoption of digital tools like i-Life. |
| Governance | Stronger audit oversight and transparent reporting. |
🟢 Conclusion: A Legacy Rebuilding Its Future
While many insurers in Bangladesh remain trapped in inertia, Sandhani Life under Nimai Kumar Saha’s leadership is charting a different course — one defined by modernization, fiscal prudence, and renewed public confidence.
Mr. Saha’s decades of experience, deep understanding of insurance operations, and commitment to digital reform have already begun to reshape the company’s internal culture.
If the transformation continues at its current pace, Sandhani Life could soon reclaim its historic reputation as “a symbol of trust and reliability” in Bangladesh’s life insurance sector —
proving that with the right leadership, even an aging institution can rediscover its strength and purpose.

- admin1@gmail.comhttps://thebusinessin.com/author/admin1gmail-com/
- admin1@gmail.comhttps://thebusinessin.com/author/admin1gmail-com/
- admin1@gmail.comhttps://thebusinessin.com/author/admin1gmail-com/
- admin1@gmail.comhttps://thebusinessin.com/author/admin1gmail-com/